
University business professor co-authors paper in ‘Journal of Corporate Finance’
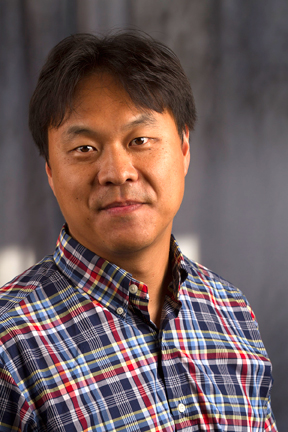
Dong Hyun Kim, assistant professor of finance in the Ohio Northern University’s Dicke College of Business Administration, has co-authored an article that has been published in “Journal of Corporate Finance,” considered one of the top journals in the finance field.
The article, titled “The Effect of Interest Rate Volatility and Equity Volatility on Corporate Bond Yield Spreads: A Comparison of Noncallables and Callables,” was co-written with Dr. Duane Stock, professor of finance at the University of Oklahoma.
The duo’s research examines the impact of interest rate volatility and equity volatility on yield spreads for noncallable and then callable bonds. Given that the total firm volatility also includes the volatility of a firm’s bonds, interest rate volatility should affect default risk. The greater the interest rate volatility, the more volatile the price of a bond. As the bond price becomes more volatile, the volatility of firm asset market value increases, thereby leading to an increase in default spread. The research finds that interest rate volatility is positively related to yield spreads on noncallable bonds.
Kim said, “We find the relationship between interest rate volatility and yield spreads is more strongly positive for junk bonds than for investment grade bonds. Investment grade bonds are unlikely to default, as pointed out by Campbell and Taksler (2003), and, as a consequence, the positive effect of interest rate volatility on the default spread should be more significant for junk bonds. In addition, we found that the average yield spread on callable bonds is greater than that on noncallable bonds, indicating that the embedded options in callable bonds are priced.”
The research also investigates whether the effect of interest rate volatility on yield spreads is greater or smaller for callable bonds than for noncallable bonds. The duo found that the effect of interest rate volatility on yield spreads is smaller for callable bonds than for noncallable bonds. Finally, the results for the impact of equity volatility upon callable bond spreads support the theory of Acharya and Carpenter (2002) more than that of King (2002).
“Journal of Corporate Finance” is a leading corporate finance journal that publishes both theoretical and empirical papers. The journal receives a large number of high-quality submissions, and its rejection rate is now more than 95 percent.
Stories Posted This Week
Thursday, September 17, 2026
- Bulldog girls soccer 0-0 tie vs. Riverdale
- Bulldog boys soccer loss vs. Riverdale
- Roundhead poet publishes third book
- Bulldog volleyball wins in four vs. Riverdale
- Sept. 15 Ada Council: Impact of big ticket pool repair, public urination ban goes into effect
- Hall named 2026 OMLA Regional Administrative Assistant of the Year
- Play Bingo with Officer Penny at the Ada Public Library
- Adult Book Group books available at APL
- Ada Schools exceed state standards on 2025-2026 Ohio Report Card
- Oct. 6 ONU Trike-A-Thon will raise funds for St. Jude's
- Antibiotic resistance: More to learn
Wednesday, September 16, 2026
Tuesday, September 15, 2026
- Bicyclist injured in hit-skip accident south of Kenton
- ODOT requests public comment on roundabout design for State Route 81/County Road 15 intersection
- Anna M. Shulaw, 105, worked for Wilson Sporting Goods
- Liberty Conservation Club fish and chicken fry, Oct. 10
- Bulldog boys soccer loss vs. Fort Jennings
- Findlay Patrol's Donovan promoted to sergeant
- Bulldog girls soccer win vs. Delphos St. John’s
- 2026 Harvest & Herb Festival Queen Court announced